Blog
Using Equity to Buy Investment Property Before a Rate Rise
The post on Instagram
Using equity to buy an investment property: the short answer
Equity is the gap between what your home is worth and what you still owe on it. When you use equity to buy an investment property, a lender may let you borrow against part of that equity (often called usable equity) to cover the deposit and purchase costs. Whether you can, and how much, depends on a valuation of your home and your borrowing power.
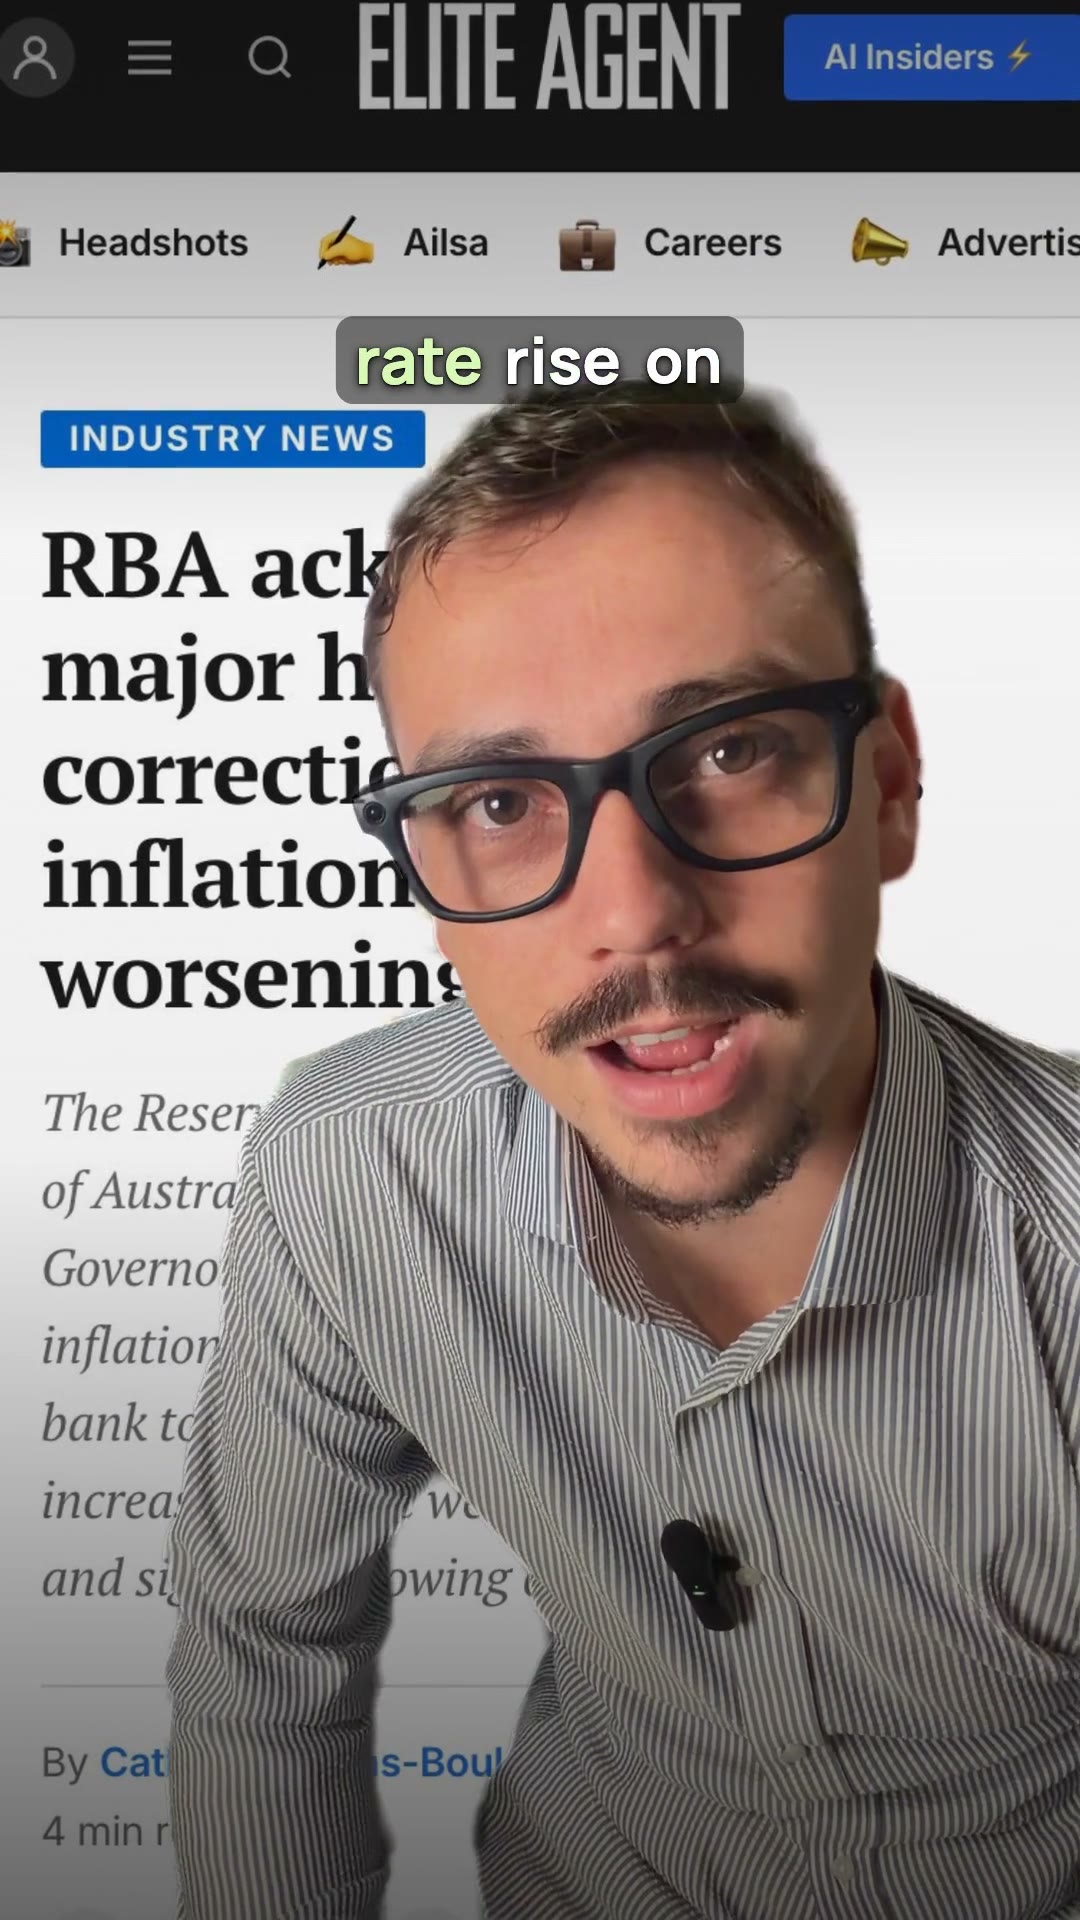
A possible interest rate rise doesn't change how equity works. It does change what repayments on your home loan and an investment loan may look like together, so it makes sense to check your numbers at higher rates before you commit. The video above walks through what the Reserve Bank of Australia (RBA) has just signalled, and our guide to using equity to invest covers the mechanics in more depth.
What the RBA has signalled about interest rates
In the video, the presenter puts it simply: "The RBA's deputy governor just said inflation looks significantly worse than they'd forecast". The translation, according to the video, is that rates might go up again.
The video also says the odds of a fifth rise on Melbourne Cup day jumped from about one in five to about fifty-fifty, and that Wednesday's inflation number decides it.
It helps to be clear about what those odds are. They reflect market expectations, not a decision. The RBA board makes the call, and its reasoning is published in its own statements. For the latest picture, check the RBA's media releases and the Australian Bureau of Statistics (ABS) inflation release rather than relying on headlines.
Why most mortgage holders aren't in crisis, according to the RBA
The video points to a part of the RBA's message that gets less attention. Per the video, the RBA says only about 2% of mortgage holders are going backwards each month, and the typical one has more than a year of cash in the bank. As the presenter says in the video, "So yes, it's tight, but it's not a crisis for most homeowners yet."
In everyday terms:
- Going backwards means a household's essential spending and mortgage repayments are more than its income, so it is running down savings or adding to debt each month.
- Cash in the bank usually means money in savings accounts and mortgage offset accounts that could cover repayments and living costs if income dropped or costs rose.
These are averages across all mortgage holders. They don't describe your household. Before you take on a second loan, look at your own buffer: how many months of repayments and living costs your savings and offset balance would actually cover.
How using equity to buy an investment property works in practice
The process usually follows a few steps, though each lender has its own policies.
- Valuation. A lender values your home. Usable equity is worked out against the maximum loan-to-value ratio the lender allows, minus what you still owe.
- Funding the deposit and costs. That usable equity may be drawn as a separate loan or a top-up to fund the deposit and purchase costs, with a separate loan for the rest of the investment property's price.
- Serviceability. Both loans need to be serviceable, meaning the lender must be satisfied you can meet repayments on everything you owe.
Under APRA guidance, lenders assess repayments using a serviceability buffer above the actual interest rate. Check APRA's current guidance or ask a lender for the figure that applies. Because lenders test repayments at higher rates, a rate rise may reduce how much you can borrow. Our guide on how much you can borrow explains what lenders look at.
Should I buy an investment property before a rate rise?
The honest answer is that nobody can reliably time the RBA. Property Guide doesn't give personal recommendations, and whether now suits you depends on your circumstances.
Instead of trying to beat a rate decision, it can help to ask:
- Could we meet repayments on both loans if rates rose again?
- How many months of buffer would we have left after the purchase?
- What would happen if the property sat vacant for a while?
- Is our income secure enough to carry a second loan?
Rushing to buy ahead of a decision can mean skipping due diligence on the property, the loan or the numbers. Waiting has trade-offs too. Moneysmart has free budgeting and mortgage calculators you can use to stress-test a budget at higher rates, and a licensed professional can look at your full position.
New build or established: what the 2026 Budget changes
The video suggests you could use the equity in your current home to buy an investment property "to take advantage of all of the tax deductions and government incentives that are being put behind buying brand new investment properties right now." That is the video's point. Whether any deduction or incentive applies to you depends on your individual circumstances.
The 2026 Budget has shifted the tax picture:
- Established homes bought after 12 May 2026: negative gearing and capital gains tax (CGT) discount changes apply from 1 July 2027. Treasury and the ATO publish the details.
- SMSF borrowing: borrowing through a self-managed super fund to buy property is banned from 10 August 2026, according to Treasury and ATO material on the Budget.
No one can promise a lower tax bill or a set deduction. Read more about the 2026 negative gearing changes and weigh up new build or established with a registered tax agent.
Costs to budget for beyond the deposit
Equity may cover the deposit, but other costs add up. Budget for:
- Stamp duty
- Legal and conveyancing fees
- Lender fees and valuation costs
- Building and landlord insurance
- Council and water rates
- Ongoing maintenance and repairs
On top of these, allow a buffer for possible rate rises on both loans, given what the RBA has signalled. Our breakdown of the real costs of buying lists what to check for your state.
Where the $150,000 combined income figure fits
The video points couples who earn over $150,000 a year combined, and who own their home or are still paying it off, to a free assessment to see where their equity stands, whatever the RBA does.
That figure describes who the assessment is aimed at. It is not a lending threshold, and it doesn't mean anyone will qualify for a loan or be able to invest. Lenders look at your whole position.
Property Guide is a free service that matches investors with vetted property investment specialists. It is not a lender, broker, agent or financial adviser, and it only covers investment property. If you're still working through the basics, browse our property investment guides.
Watch: what the video covers
- The RBA's deputy governor said inflation looks significantly worse than forecast, so rates might go up again.
- The odds of a fifth rise on Melbourne Cup day jumped from about one in five to about fifty-fifty.
- The RBA says only about 2% of mortgage holders are going backwards each month, and the typical one has more than a year of cash in the bank.
- It's tight but not a crisis for most homeowners yet, and Wednesday's inflation number decides it.
- Couples earning over $150,000 combined who own their home can take a free assessment to see where their equity stands.
This article is general information only and is not personal financial, tax or legal advice. It does not take your circumstances into account, so speak to a licensed professional before making any investment decision.
Frequently asked questions
Can I use the equity in my home to buy an investment property if I still have a mortgage?
Often, yes. Equity is the difference between your home's value and what you owe, so you can have equity while still paying off a loan. How much a lender lets you use depends on a valuation, its loan-to-value limits and your borrowing power.
Does a rate rise reduce how much I can borrow for an investment property?
It may. Lenders assess repayments with a serviceability buffer above the actual rate, in line with APRA guidance, so higher rates can lower the amount they are willing to lend. Ask a lender or check APRA for current settings.
Should I wait for the RBA decision before using equity to invest?
Nobody can reliably time the RBA. It is usually more useful to test whether you could manage repayments on both loans at higher rates and how much buffer you would keep. It depends on your circumstances, so talk to a licensed professional.
Do the 2026 negative gearing changes apply to new builds or only established homes?
The 2026 Budget changes to negative gearing and the CGT discount apply from 1 July 2027 to established homes bought after 12 May 2026. Check Treasury and ATO material, and a registered tax agent, for how the rules apply to a specific property.
Is the $150,000 combined income in the video a requirement to invest?
No. It describes who the free assessment is aimed at. It is not a lending threshold and doesn't mean anyone will qualify for a loan.