Blog
Are House Prices Falling in Australia? Which Markets Are Actually Down
Yes, house prices are falling in Australia on a national basis. You may have seen headlines like "House values fall for the sixth month in a row". But that headline only tells part of the story, and the fuller answer depends on which market you mean.
The post on Instagram
Are house prices falling in Australia?
At the national level, yes. According to Cotality's Home Value Index for September 2026 (released 1 October 2026, and the source quoted in the video above), national values are down about 5% from the March 2026 peak (5.2%), and Sydney is down 7% on a year ago (7.0%).
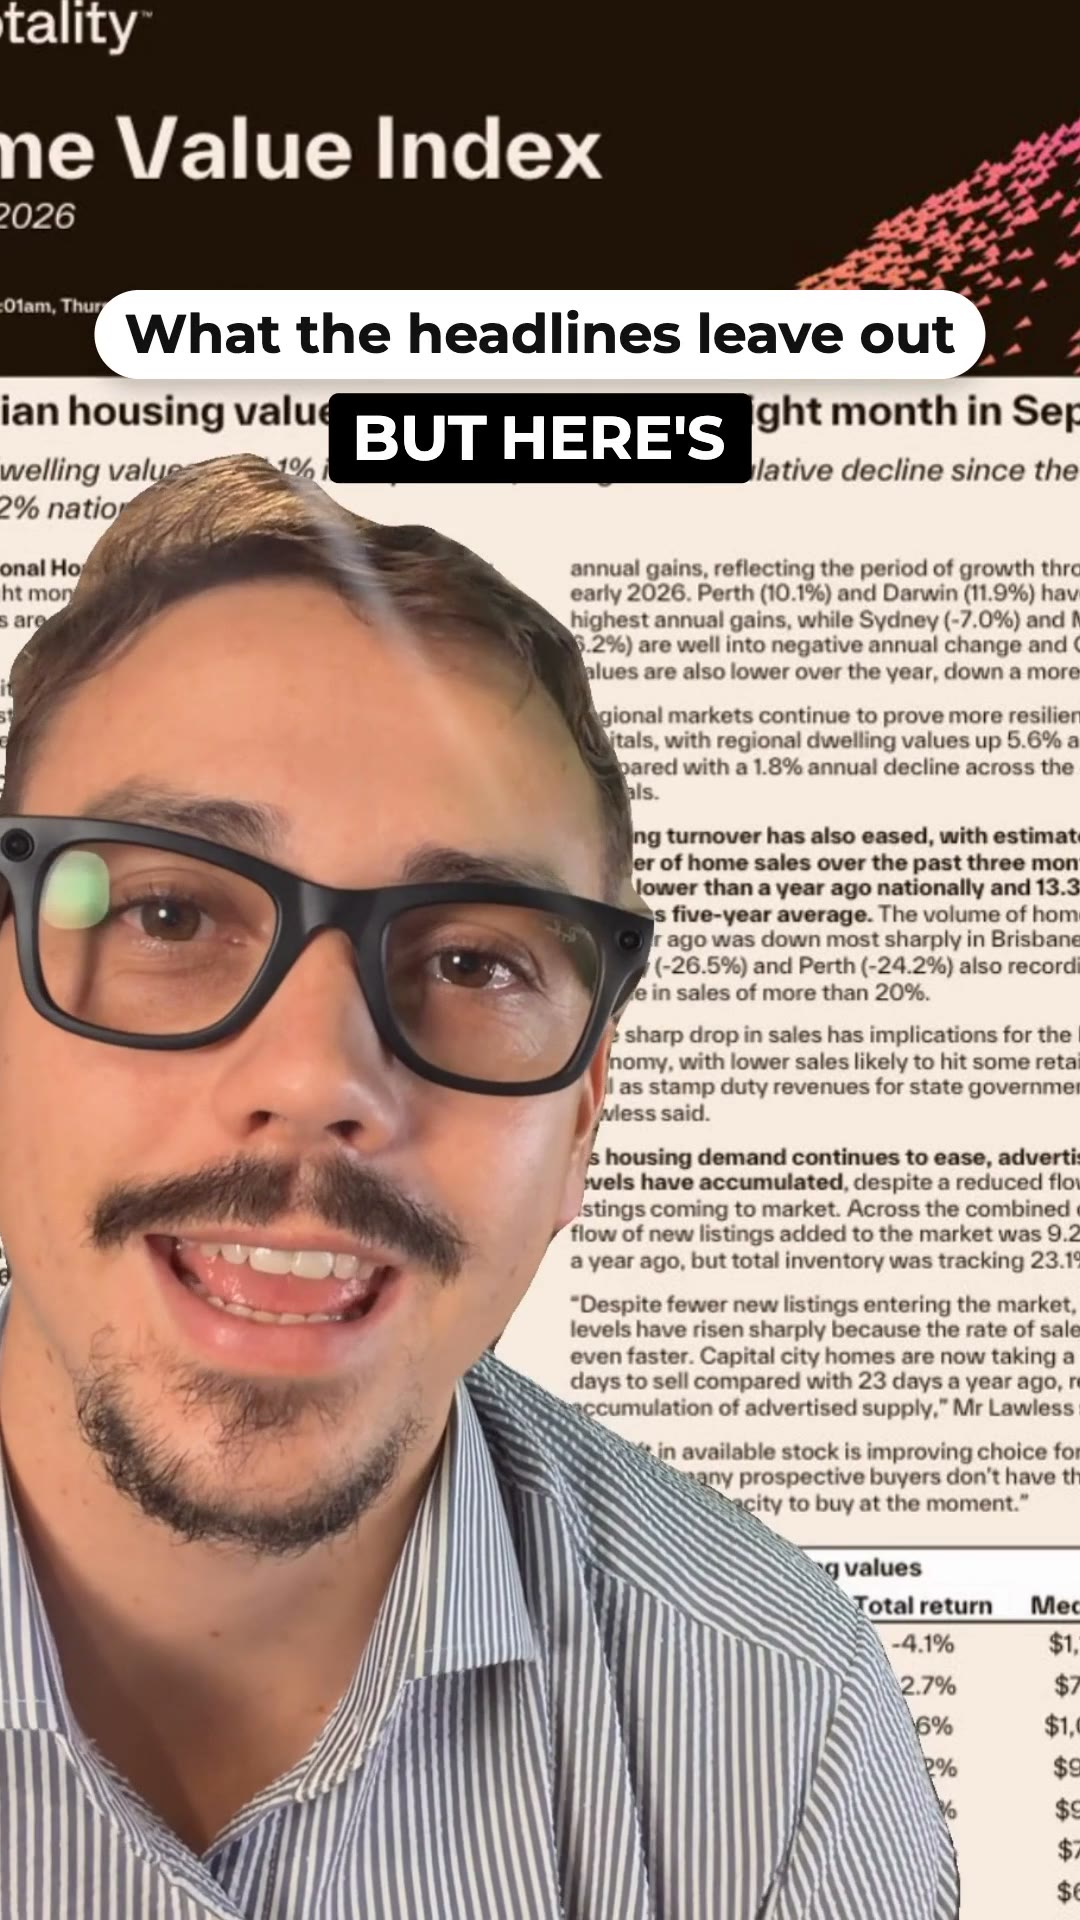
Over that same year, though, other parts of the country went the other way:
- Perth is up 10%
- Darwin is up 12%
- Regional Australia is up nearly 6%
The short takeaway: a national figure is an average of many different markets. Some of those markets are falling and some are rising, sometimes at the same time.
Why one national figure hides dozens of property markets
As the video puts it, "There isn't just one property market in Australia, there's dozens and they're all moving in different directions."
That happens because property prices are shaped by local conditions. Capital cities and regional areas, and houses and units, can respond differently to things like:
- how many homes are being built or listed for sale in the area
- how many people want to buy or rent there
- population changes, including people moving between states or out of the cities
- the strength of the local economy and jobs
- borrowing conditions, such as interest rates and lender rules
Because of this, a national average can fall while some areas rise. A headline about "Australian house prices" may not describe the area you own in, or the area you're thinking of buying in.
It's worth being clear about one thing. The rises in Perth, Darwin and regional Australia describe what happened over a past year. Past growth figures don't predict future returns, and no one can say whether any area will keep rising or start falling.
How to read a 'prices are falling' headline
The video offers a simple test for the next time this comes up: "So the next time someone asks you, is the market crashing, you say which one?"
When you see a price headline, run through a few quick checks:
- Which area does it cover? National, a single capital city, or regional areas?
- Which period does it measure? Is the change measured from a peak, or year on year?
- Which property type? Houses, units, or both combined?
The period matters more than it might seem. "Down from the March peak" and "down on a year ago" measure different things. The first compares today with the highest recent point. The second compares today with the same time last year. So figures quoted in different ways are not always directly comparable.
For wider context, look to reputable sources. The Reserve Bank of Australia (RBA) and the Australian Prudential Regulation Authority (APRA) publish information on interest rates and lending conditions, and Moneysmart has plain-English material on investing basics.
Should I buy an investment property now?
A headline on its own, whether prices are falling or rising, isn't enough to make that decision. Whether an investment property suits you depends on your circumstances, your budget, how much you may be able to borrow and how long you plan to hold the property.
No one can say which way a market will move next. So rather than trying to pick the moment, it usually helps to work through the things you can actually check:
- The local market, not the national figure. Look at how the specific area and property type you're considering has been moving, and why.
- Your total costs. Stamp duty, legal fees, inspections and ongoing costs all add up. Our guide to the real costs of buying walks through them.
- Your borrowing capacity. Lenders assess income, expenses and existing debts. See how much you can borrow for how this usually works.
- Your buffer. Could you keep paying the loan if rates rose or the property sat empty for a while?
Treat these as questions to take to a licensed professional, rather than a reason to buy or wait.
Why the type of investment property can matter even more
The video moves from where you buy to what you buy: "Now the type of property you buy can be even more important." It uses a brand new property as its example.
That point carries extra weight after the 2026 Budget. According to Treasury and the ATO, negative gearing and capital gains tax (CGT) discount changes apply from 1 July 2027 to established homes bought after 12 May 2026. In other words, new and established investment properties may now be treated differently for tax.
If you buy an established home after 12 May 2026, the old negative gearing and CGT discount rules don't carry over to it. How the rules apply to any one property, and whether they make any difference to your tax, depends on your circumstances, so check the details with a registered tax agent. Our guide to the 2026 negative gearing changes explains them in more detail.
If you were thinking of investing through a self-managed super fund (SMSF), note that the Budget also includes an SMSF borrowing ban from 10 August 2026. The ATO and Treasury are the places to check how this applies.
For a side-by-side look at the trade-offs, see our guide on whether to choose a new build or established investment property.
Using home equity to buy an investment property
Equity is the gap between what your home may be worth and what you still owe on it. Some lenders may let you use part of that equity towards the deposit on an investment property, depending on your circumstances and their assessment.
This is where the "which market?" question becomes personal. Your home's value, and so your equity, is shaped by how your own local market has moved, not by a national headline. A national fall doesn't automatically mean your equity has shrunk, and a national rise doesn't mean it has grown.
The video is aimed at couples who earn over $150,000 combined and own their home, and says they could use their equity to buy an investment property. That's who the message speaks to, not a test for who qualifies. Whether a lender approves a loan depends on its own assessment of your situation.
There are risks to weigh up too:
- Borrowing against your home increases your total debt.
- Your home becomes security for the extra borrowing.
- Property values can fall as well as rise, which can reduce your equity.
Our guide to using equity to invest covers how the process usually works.
Property Guide is a free service that matches investors with vetted property investment specialists. We're not a lender, broker, agent or financial adviser, and we don't give personal financial, tax or legal advice.
Where to go from here
National price falls are real, but they're an average across many markets moving in different directions. So when you hear the market is crashing, ask "which one?", then look at the property type and your own position before deciding anything.
When you're ready to dig further, browse our property investment guides.
Watch: what the video covers
- It opens with the headline "House values fall for the sixth month in a row" and says there's more to the story.
- It gives the falls from Cotality's September 2026 Home Value Index: national values down 5% from the March peak, and Sydney down 7% from a year ago.
- Over that same year, it notes Perth up 10% (Cotality: 10.1%), Darwin up 12% (11.9%) and regional Australia up nearly 6% (5.6%), and says there are dozens of markets moving in different directions.
- It says the type of property you buy can be even more important, using a brand new property as its example.
- It ends with a message for couples earning over $150,000 who own their home, about using equity to buy an investment property.
This article is general information only and is not personal financial, tax or legal advice. It does not take your circumstances into account, so speak to a licensed professional before making any investment decision.
Frequently asked questions
Are house prices falling everywhere in Australia?
No. According to the video, national values are down about 5% from the March peak and Sydney is down 7% on a year ago, but over the same year Perth is up 10%, Darwin is up 12% and regional Australia is up nearly 6%.
Does a national price fall mean my home's equity has gone down?
Not necessarily. Your equity depends on your home's value in your local market and what you still owe, not on the national average. A lender's valuation is the usual way to find out.
Is it a good idea to buy an investment property while prices are falling?
A headline alone isn't enough to decide. No one can say where a market will go next, so it depends on your circumstances, budget, borrowing capacity and time frame. Talk it through with a licensed professional.
How do the 2026 Budget tax changes affect new and established investment properties?
According to Treasury and the ATO, negative gearing and CGT discount changes apply from 1 July 2027 to established homes bought after 12 May 2026, so new and established properties may be treated differently. Check with a registered tax agent.
Can I use the equity in my home to buy an investment property?
Some lenders may let you use part of your equity towards a deposit, depending on your circumstances and their assessment. It increases your total debt and uses your home as security, so weigh the risks first.